What Happens If My Malibu Home Appraises Below the Sale Price?
A low appraisal doesn’t automatically end your Malibu home sale or change the price you agreed to. It can reduce the amount the buyer’s lender will finance, so the next step is to confirm the actual cash shortfall and review the contract. Depending on the terms, the buyer may bring more cash, both parties may agree to a different price, or the buyer may have a right to cancel. Consumer Financial Protection Bureau
Find out what changed for the buyer
When an appraisal comes in low, the first number everyone sees is the difference between the appraised value and the contract price. The more useful number is how much additional cash the buyer actually needs to close. Ask the buyer to confirm that figure with their lender before you discuss a price change.
Here’s a hypothetical example. Say you’re under contract at $4 million, and the buyer planned to borrow $2.8 million. If the home appraises at $3.8 million and the lender will lend up to 70% of that value, the maximum loan in this example falls to $2.66 million. If the price stays the same, the buyer needs $140,000 more cash than originally planned, before closing costs. The appraisal gap is $200,000; the financing shortfall is $140,000. Actual loan terms vary.
Review the comparable sales through a Malibu lens
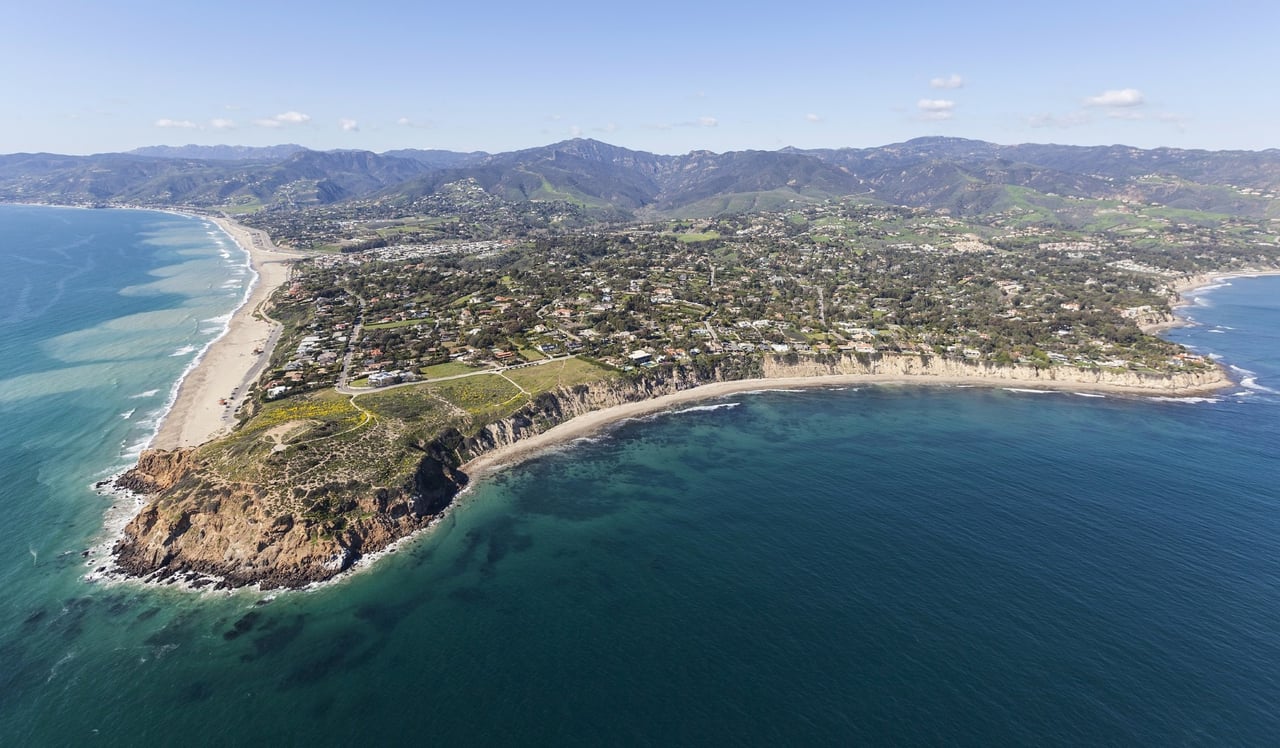
On a distinctive Malibu property, it’s worth looking closely at what the appraiser used for comparison. A blufftop home in Point Dume and a house farther inland may have similar square footage, but the bluff setting, usable outdoor space, and documented access rights can make them different choices for buyers. For an ocean-view home, look at whether the sales used in the report offer a similar outlook from the main living areas.
Fannie Mae’s comparable-sales guidance emphasizes similar physical and legal characteristics. A nearby sale is useful when it shares the features buyers are weighing; a sale farther away may be more informative if it competes for the same buyers and the comparison is explained. selling-guide.fanniemae.com
If there’s a concrete issue, such as an incorrect finished area or a relevant closed sale the report didn’t address, gather the supporting records. The buyer can ask the lender about a reconsideration of value, the formal process for requesting a review. A clear factual correction or a well-supported comparable gives the lender something specific to evaluate; a review doesn’t guarantee a revised value. selling-guide.fanniemae.com
Check the deadlines before negotiating
I’d review the appraisal and financing provisions as soon as the issue comes up. Check which contingencies are still in place, what they cover, and when any response is due. If the lender needs time to review new information, discuss whether a written extension makes sense before a deadline passes.
Once you know the actual financing shortfall, compare your options. If the buyer can bring the additional cash, the price may stay intact. If the buyer needs some relief, you might agree on a smaller price reduction than the full appraisal gap. Weigh any concession against the time and uncertainty of going back on the market, especially if the next buyer is likely to have similar financing needs.
Frequently asked questions
Do I have to lower my price to the appraised value?
A low appraisal does not automatically reset the contract price. A price reduction is a negotiation, and the agreement governs each side’s rights if you can’t reach a resolution. Consumer Financial Protection Bureau
Can I prepare for the appraisal before I list?
Yes. Organize records for significant improvements, any documented access rights you plan to market, and the sales that best explain your pricing. Keep the information easy to verify.
Does an all-cash offer avoid this issue?
It removes the lender’s appraisal requirement from the equation, but a cash buyer can still request an appraisal or include a valuation contingency. Read the offer itself before assuming the sale is insulated from an appraisal issue.
If you’re preparing to sell in Malibu, reach out to Stephen Udoff to discuss the sales that support your price and how to evaluate appraisal terms before accepting an offer.